Worsened access to the U.S. market limits Canadian firms’ ability to scale up and strengthen productivity, making it more difficult to compete in markets around the world.
Canadians should ask what remains after drawing investor dollars, and what is exchanged: wealth we still own, or a bigger ledger built on corporate subsidies and asset sales?
A comprehensive community finance strategy would move Canada to a connected national system capable of mobilizing billions in private and community investment to create jobs and housing solutions, support entrepreneurs, advance reconciliation, and boost local economies.
Our country produces world-class companies and then watches them get acquired, relocate, or stall out before they reach their potential.
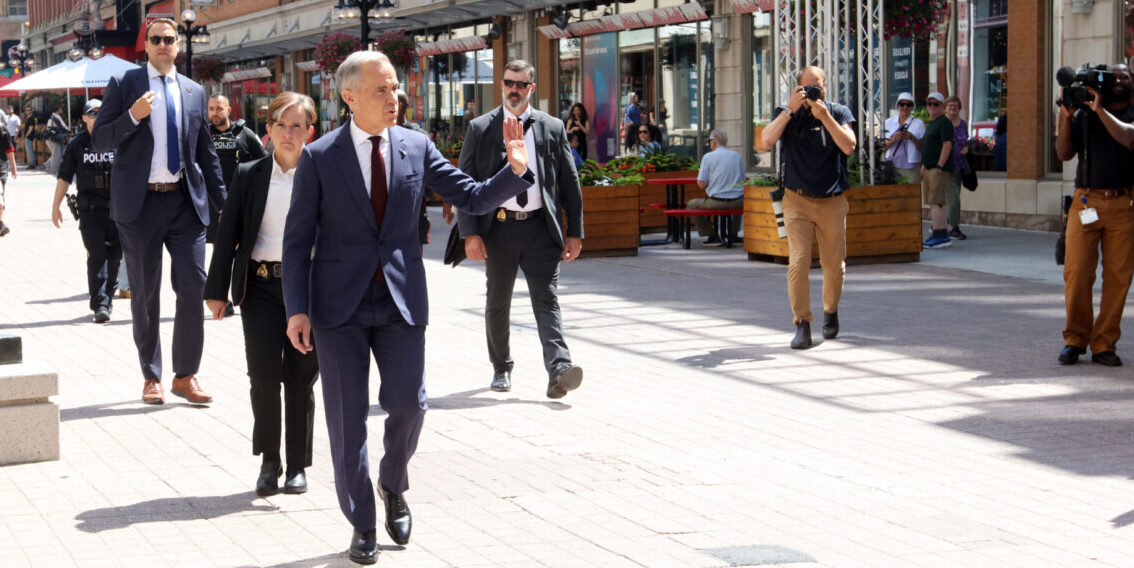
The dispute involving 42 Ottawa and seven Montreal security officers prompted the Bank of Canada to close its Montreal facility and move critical and time-sensitive operations to Toronto, while the CIRB has twice ordered it to stop using replacement workers to perform striking officers’ work.

Routledge says our banks are not thinking of a new business model for a new kind of economy. That’s a big problem that could cost Canada dearly. To build this new economy, we need a new kind of financial system and it has to be a national priority if we are to be a prosperous and sovereign nation.

A bold, national, community finance strategy would unlock billions of dollars in private capital, create jobs, and ensure prosperity reaches every corner of the country.

Canada cannot afford another half-built system. In order to call this framework “open banking,” it must immediately apply to business accounts. Anything less is branding.

Economic success will only succeed if we become an innovation nation, not a petrostate. We have great talent in Canada and many ambitious entrepreneurs with world-class ideas. That is where we should be putting our economic muscle. And this is Carney’s test.

A new pathway is required, shifting away from heavy reliance on budgetary funding and subsidies, and toward more innovative resource mobilization and access to capital.

The 50-basis-point cut, reducing the rate to 3.75. per cent, is ‘to support economic growth and keep inflation close to the middle’ of the one per cent to three per cent range, the Bank explained.

While real wages stagnate, bankers and shareholders are getting rich by doing worse things than would land the average person in prison for life.

When the executives of Canada’s Big Five testify at the House Environment Committee on June 13, it will be an opportunity to cut through the banks’ greenwashing and redwashing.

‘I don’t think people are going to wake up tomorrow feeling better about the government than they felt yesterday,’ says former Liberal PMO staffer Alex Kohut.

Let’s hope this long economic winter will have equipped us to make the next ones less harsh, and that the spring finally comes back in full force.

Whether an explicit broadening of the BoC’s mandate is needed is far from clear, but current circumstances support the need for flexibility in monetary policy frameworks.

The general consensus among economists is that central bank independence is necessary for good inflation control.

Politicians have many competing priorities, and may not always place a high enough importance on low and stable inflation.

Central banks, particularly those with a stated goal of price stability, must act decisively and swiftly in response to inflation to preserve their credibility.

There have always been conflicting objectives for the financial and monetary sides of the economy.

The consumer-driven banking framework will help Canadians manage their credit cards, apply for loans, and save for their futures much more easily.

The government will finally advance Canada towards consumer-driven finance when it tables legislation signalled in April’s budget.

In a survey commissioned by Interac for Data Privacy Week, 77 per cent of respondents said that they feel that their personal data is more exposed than ever before.